Encyclopedia
Economics & Finance
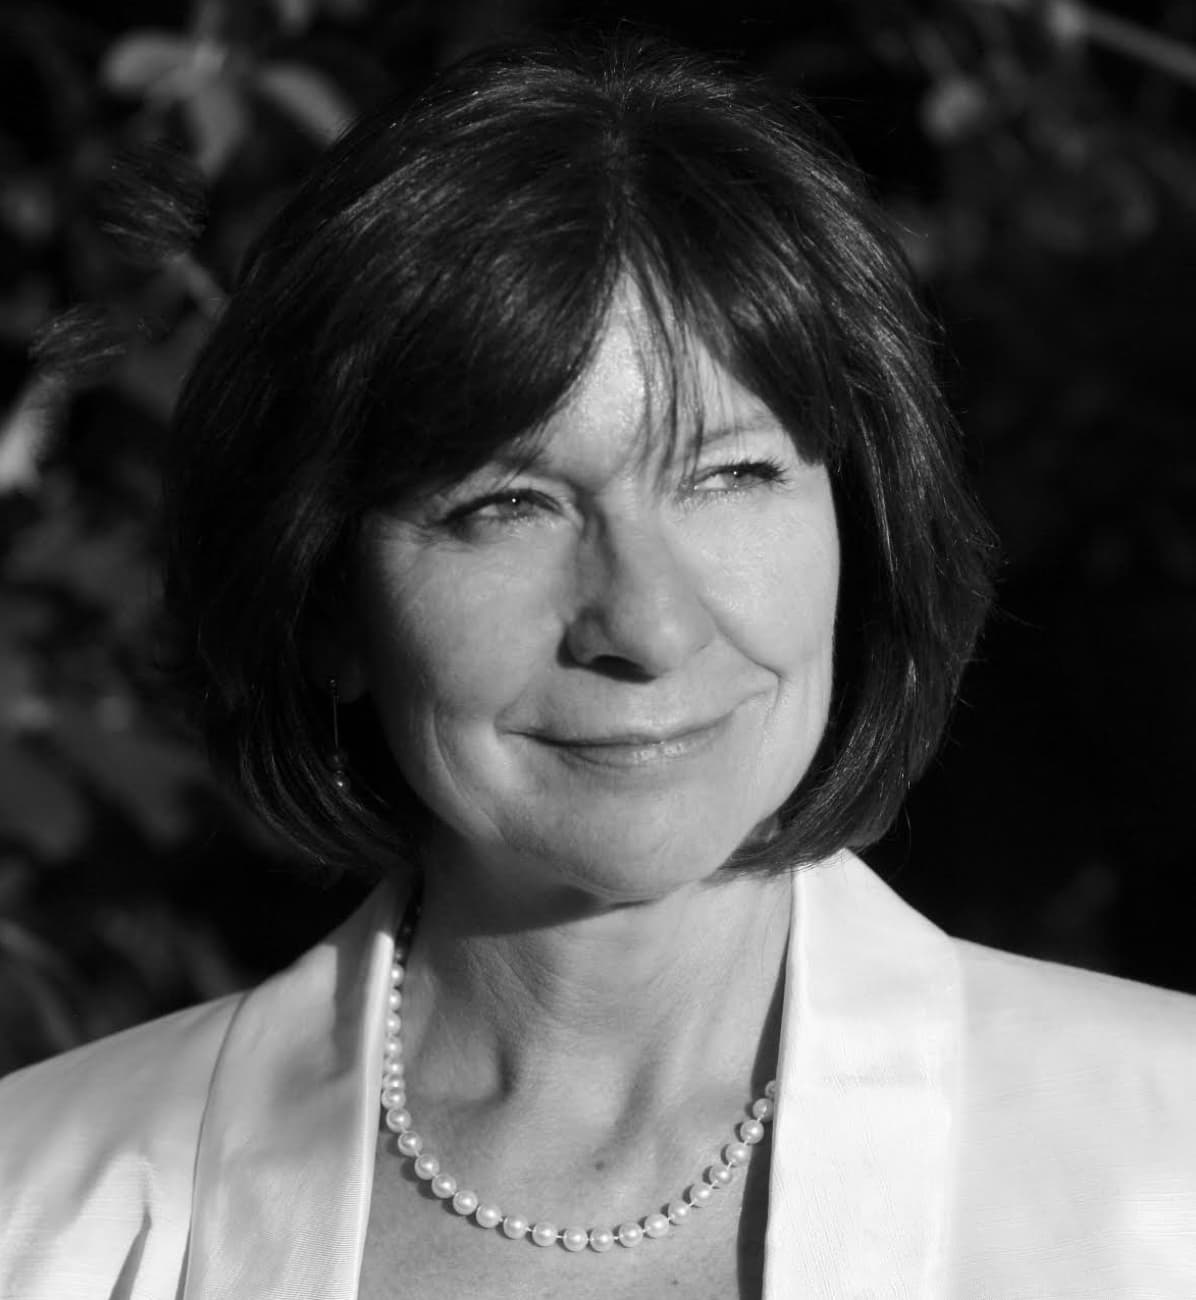
Carol Alexander
Professor of Finance, University of Sussex
Carol Olivia Alexander is a Professor of Finance at the University of Sussex and a Visiting Professor at Peking University.
She has authored 75 journal articles on various topics in finance. You can find her textbooks Market Models: A Guide To Financial Data Analysis here (https://www.amazon.com/Market-Models-Guide-Financial-Analysis/dp/0471899755) & Market Risk Analysis here (https://www.amazon.com/Market-Risk-Analysis-Carol-Alexander/dp/0470997990).
Alexander has taught courses on econometrics, game theory, mathematics, and finance at the University of Sussex, the University of Reading, TU Munich, and Peking University.
She has held private sector positions as Director and Head of Market Risk Modelling for Nikko Securities, a Director of Algorithmics Inc, and as a Bond Analyst for Phillips & Drew (City of London).
Alexander has consulted as an expert witness for White and Case (Washington D.C.) and Richards Butler (City of London). She is an affiliated consultant with Fideres in London, New York, Frankfurt and Johannesburg.
She has designed and implemented mathematical models for pricing, trading, hedging, and risk assessment for a wide range of asset management, stock exchange, and banking clients, including Credit Agricole, the New York Stock Exchange, the Intercontinental Exchange, and the FTX.US Exchange.
You can find her blog here.
Courses Taught: 1985 - 1998; Econometrics | Postgraduate | Department of Economics | University of Sussex; Mathematics for Economists | 2nd Year UnderGraduate | Department of Economics | University of Sussex; Mathematics for Biologists | 1st Year UnderGraduate | Department of Mathematics | University of Sussex; Group Theory | 2nd Year UnderGraduate | Department of Mathematics | University of Sussex; Linear Algebra | 1st Year UnderGraduate | Department of Mathematics | University of Sussex; Microeconomics | 2nd Year UnderGraduate | Department of Economics | University of Sussex; Macroeconomics | 2nd Year UnderGraduate | Department of Economics | University of Sussex; Statistics | 2nd Year UnderGraduate | Department of Mathematics | University of Sussex; Game Theory | Postgraduate | Department of Mathematics | University of Sussex; 2000 - 2012; Market Risk | Postgraduate | ICMA Centre | University of Reading; Volatility Analysis | Postgraduate | ICMA Centre | University of Reading; Quantitative Methods for Finance | Postgraduate | ICMA Centre | University of Reading; 2012 - 2018; Topics in Finance | Postgraduate | Department of Mathematics | University of Sussex; Hot Topics in Finance | MBA | Business School | University of Sussex; Essential Quantitative Finance | Postgraduate | Business School | University of Sussex; Advanced Quantitative Finance | Postgraduate | Business School | University of Sussex; Financial Risk Management | Undergraduate | Business School | University of Sussex; Blockchains and Crypto Assets | Undergraduate & Postgraduate | Business School | University of Sussex; 2018; Advanced Volatility Analysis | Postgraduate | TU Munich; 2019; Financial Risk Management | Postgraduate | Business School | Peking University; 2018 - Present; Financial Risk Management | Undergraduate | Business School | University of Sussex; Blockchains and Crypto Assets | Undergraduate & Postgraduate | Business School | University of Sussex.
- Education
- Ph.D. Algebraic Number Theory, University of Sussex · M.Sc. Mathematical Economics & Econometrics, London School of Economics · B.Sc. Mathematics with Experimental Psychology, University of Sussex
- Topics
- Mathematics · Economics · Finance · Financial Risk Management · Cryptocurrencies · Blockchains · NFTs · Regulators · Hedge Funds · High Frequency Data Analysis · Pricing and Hedging Financial Instruments · Volatility Analysis · Investment Strategies · Benchmarking · Portfolio Management · 1990 – 1991 First Generation GARCH Models · Hill Samuel Bank · London · 1992 Volatility Trading Models · Equitable House Investments · 1994 – 2003 Hedge Fund Strategy Design · Pennoyer Capital Management · New York · 1996 – 1997 Spot-Futures Arbitrage Models · ED&F Man · 1996 Internal Value-at-Risk Model Design · Shell Pension Fund · Netherlands · 1997 – 1998 Orthogonal GARCH Models · Robert Fleming
In the Encyclopedia16
- Blog · Apr 11, 2023How Will The Shanghai Fork Affect The De-Fi Crypto Ecosystem?
- Blog · Dec 16, 2022How Should Binance Prove It Is Solvent?
- Blog · Jul 7, 2022Why This Crypto Crash Is Different
- Blog · Jan 17, 2022Binance Spoofy Bots Cause Mass Liquidations
- Blog · Nov 14, 2021The Tether-Binance Axis and the Great Crypto Crash of 2022
- Blog · Nov 14, 2021Binance Still Onboarding Fiat and Offering 50X to 125X Leverage
- Blog · Nov 13, 2021Tether and Bitcoin Ponzi Ecosystem Stage 2: DOWN
- Blog · Nov 12, 2021Tether and Bitcoin Ponzi Ecosystem Stage 1: UP
- Blog · Oct 16, 2021Tether Props up Toxic Crypto Carousel
- Blog · Aug 20, 2021Trading Operations of the Binance Insurance Fund
- Blog · Jul 9, 2021Almost All Bitcoin Price Transmission Comes from Binance
- Blog · Jul 4, 2021Almost all Bitcoin Volatility Transmission Comes from Binance
- Blog · Jun 14, 2021Here’s Why Cryptocurrency Doesn’t Crash at Weekends
- Blog · May 28, 2021Bitcoin Variance Swaps
- Blog · Apr 29, 2021Why Britcoin CBDC Will Take Many Years To Launch
- Blog · Apr 29, 2021Is Dogecoin as Dodgy as Elon Musk?
Talks & video39
- What Are NFTs? | Carol AlexanderVimeo
- Why Are NFT Collections So Expensive? - Carol AlexanderVimeo
- What Is The Future For NFTs? - Carol AlexanderVimeo
- 9th Annual Round Table of the International Financial Risk Institute (IFRI, London)2003
- 1st International Congress on Financial and Derivatives Markets, (BM&F, Brazil)2003
- Risk and Return Russia, (Moscow)2007
- Quant Congress Europe (London)2007
- Quant Congress Europe (Paris)2008
- Quant Congress Europe (Amsetrdam)2009
- Quant Congress USA (New York)2009
- FOW Derivatives World (London), Post-Crisis Risk Measurement (CFA UK)2010
- Changing Risk Landscape, Financial Times (London)2010
- Model Risk Validation (Paris)2011
- PRMIA 10th Anniversary Global Risk Conference (New York)2012
- Royal Institution 14-10 Club (London)2012
- KPMG Chair Address to Chief Risk Officers, (Frankfurt)2016
- QuantMinds International (Hamburg)2019
- Cryptocompare Digital Asset Summit (London)2019
- QuantMinds International (virtual)2020
- Westminster Business Forum Policy Conference: Fintech in the UK (virtual)2020
- Quant Insights (virtual)2020
- New Directions in Risk Management, Frankfurt2003
- German Finance Association 9th Annual Congress, Augsburg2004
- Campus for Finance, Germany2004
- Quantitative Methods in Finance Conference, Sydney2005
- Third Annual Mathematics in Finance International Conference, Kruger, South Africa2008
- HVB-Institute for Mathematical Finance, Munich2010
- Ninth Applied Financial Economics Conference, Greece2012
- Fields Institute, Toronto, Canada2013
- Fourth Conference on Non-linear Dynamics and Financial Markets, Paris2017
- Fifth International Symposium in Computational Economics and Finance2018
- EURO2018: 29th Annual European Conference of Operational Research Societies2018
- Sustainable Finance Conference, Birmingham University (virtual)2021
- Financial Economics Meeting: Post-Crisis Challenges (virtual)2021
- Brazilian Finance Meeting (virtual)2021
- 7th International Young Finance Scholar’s Conference (virtual)2021
- Cryptocurrency Research Conference (virtual)2021
- 4th Asia Conference on Business and Economic Studies, Vietnam2022
- 4th International Conference on Computational Finance, Germany2022
Selected publications151
- 2022Alexander, C., Deng, J., Feng, J. and H. Wan (2022) Net Buying Pressure and the Information in Bitcoin Option Trades. Journal of Financial Markets, Forthcoming.
- 2022Alexander, Han, Y. and X. Meng (2022) Static and Dynamic Models for Multivariate Distribution Forecasts. International Journal of Forecasting, Forthcoming.
- 2022Alexander, C., Meng, X. and W. Wei (2022) Targetting Kollo Skewness with Random Orthogonal Matrix Simulation. European Journal of Operational Research, 299, 362 - 376
- 2022Alexander, C., Coulon, M., Han, Y. and X. Meng (2022) Evaluating the Discrimination Ability of Proper Multi-Variate Scoring Rules. Annals of Operations Research, Open Access.
- 2022Alexander, C. and M. Dakos (2022) Assessing the Accuracy of Exponentially Weighted Moving Average Models for Value-at-Risk and Expected Shortfall of Crypto Portfolios. SSRN.
- 2022Alexander, C. and I. Imeraj (2022) Delta Hedging Bitcoin Options with a Smile. SSRN.
- 2021Alexander, C., Deng, J. and B. Zou (2021) Hedging with Bitcoin Futures –The Effect of Liquidation Loss Aversion and Aggressive Trading. ArXiv.
- 2021Alexander, C., Heck, D. and A. Kaeck (2021) The Role of Binance in Bitcoin Volatility Transmission. ArXiv.
- 2021Alexander, C., Coulon, M., Han, Y. and X. Meng (2021) Evaluating the Discrimination Ability of Proper Multi-Variate Scoring Rules. Annals of Operations Research, In Press.
- 2021Alexander, C., Chen, X. and C. Ward (2021) Risk-Adjusted Valuation for Real Option Decisions. Journal of Economic Behaviour and Organisation, In Press.
- 2021Alexander C. and X. Chen (2021) Model Risk in Real Option Valuation Annals of Operations Research, 299(1), 1025-1056
- 2021Alexander, C. and A. Imeraj (2021) The Bitcoin VIX and its Variance Risk Premium. Journal of Alternative Investments, 23 (4) 84-109
- 2021Alexander, C. and J. Rauch (2021) A General Property for Time Aggregation. European Journal of Operational Research, 291(2), 536-548
- 2021Alexander, C. and E. Lazar (2021) The Continuous Limit of Weak GARCH. Econometric Reviews 40(2), 197-216
- 2021Alexander, C., Lazar, E. and S. Stanescu (2021) Analytic Moments for GARCH Processes. International Journal of Forecasting 37(1), 105-124
- 2021– present Scientific Advisory Board Member, Fintech and AI in Finance, European Cooperation in Science and technology (COST) Action
- 2020Alexander, C. and D. Heck (2020) Price Discovery in Bitcoin: The Impact of Unregulated Markets. Journal of Financial Stability 50, 1-18.
- 2020Alexander, C., Choi, J., Massie, H. and S. Sohn (2020) Price Discovery and Microstructure in Ether Spot and Derivatives Markets. International Review of Financial Analysis, 71
- 2020Alexander, C. and D. Cumming eds. (2020) Corruption and Fraud in Financial Markets: Malpractice, Manipulation and Misconduct. Wiley
- 2019Alexander C., Choi, J., Park, H., and S. Sohn (2019) BitMEX Bitcoin Derivatives: Price Discovery, Informational Efficiency and Hedging Effectiveness. Journal of Futures Markets, 40(1) 23-43
- 2019Alexander C. and M. Dakos (2019) A Critical Investigation of Cryptocurrency Data and Analysis Quantitative Finance, 20(2), 173-188
- 2019Alexander C., Kaeck, A. and Sumawong, A. (2019) A Parsimonious Parametric Model for Generating Margin Requirements for Futures European Journal of Operational Research, 273(1), 31-43
- 2018– present Steering Committee Member, Centre for Financial Industries, Fields Institute
- 2017Leontsinis, S., and C. Alexander (2017) Arithmetic Variance Swaps Quantitative Finance, 17(4), 551-569.
- 2016Alexander, C., Korovilas, D. and J. Kapraun (2016) Diversification with Volatility Products Journal of International Money and Finance, 65, 213-235
- 2015Alexander, C., J. Kapraun and Korovilas, D. (2015) Trading and Investing in Volatility Products Financial Markets, Institutions and Instruments, 24(4), 313-347
- 2015– present Advisory Editor, Journal of Commodity Markets, Elsevier
- 2013Alexander, C., Lazar, E. and S. Stanescu (2013) Forecasting VaR using Analytic Higher Moments for GARCH Processes International Review of Financial Analysis 30, 36-45
- 2013Kaeck, A. and C. Alexander (2013) Stochastic Volatility Jump-Diffusions for European Equity Index Dynamics. European Financial Management 19(3), 470-496
- 2013Alexander, C. and D. Korovilas (2013) Volatility Exchange-Traded Notes: Curse or Cure? Journal of Alternative Investments 15(2), 52-70
- 2013Kaeck, A. and C. Alexander (2013) Continuous-time VIX Dynamics: On the Role of Stochastic Volatility of Volatility. International Review of Financial Analysis 28, 45-46
- 2013Alexander, C., Propoczuk, M. and A. Sumawong (2013) The (De)merits of MinimumVariance Hedging: Application to the Crack Spread. Energy Economics 36, 698-707
- 2013– present Co-Editor of Journal of Banking and Finance, Elsevier
- 2012Ledermann, D. and C. Alexander (2012) Further Properties of Random Orthogonal Matrix Simulation. Mathematics and Computers in Simulation 83, 56-79
- 2012Kaeck, A. and C. Alexander (2012) Volatility Dynamics for the S&P 500: Further Evidence from Non-affine, Multi-factor Jump Diffusions. Journal of Banking and Finance 36(11), 3110-3121
- 2012Alexander, C. and J-M. Sarabia (2012) Quantile Uncertainty and Value-at-Risk. Risk Analysis: An International Journal 32(8), 1293-1308
- 2012Alexander, C., Cordeiro, G., Ortega, E. and J-M. Sarabia (2012) Generalized BetaGenerated Distributions. Computational Statistics and Data Analysis 56(6), 1880-1897
- 2012Alexander, C. and A. Venkatramanan (2012) Analytic Approximations for Multi-Asset Option Pricing. Mathematical Finance 22(4), 667-689
- 2012Alexander, C. and A. Kaeck (2012) Does Model Fit Matter for Hedging? Evidence from FTSE 100 Options. Journal of Futures Markets 32(7), 609-638
- 2012Alexander, C., A. Rubinov, M. Kalepky and S. Leontsinis (2012) Regime-Dependent Smile-Adjusted Delta Hedging. Journal of Futures Markets. 32(3), 202-229
- 2011Venkatramanan, A. and C. Alexander (2011) Closed-form Approximations for Spread Options. Applied Mathematical Finance. 18(5), 447-472
- 2011Ledermann, W., Alexander, C. and D. Ledermann (2011) Random Orthogonal Matrix Simulation. Linear Algebra and its Applications, 434, 1444-1467
- 2011External Assessor, PhD Programme in Economics and Finance, St. Gallen University
- 2011– 2013 Editorial Board, Journal of Investment Strategies
- 2011– 2013 Member of CFA Advisory Council
- 2009Alexander, C. and E. Lazar (2009) Modelling Regime-Specific Stock Price Volatility. Oxford Bulletin of Economics and Statistics, 71:6, 761 - 797
- 2009Alexander, C., A. Kaeck and L. Nogueira (2009) Model Risk Adjusted Hedge Ratios. Journal of Futures Markets, 29:11, 1021-1045
- 2008Alexander, C. and E. Sheedy (2008) Developing a Stress Testing Framework based on Market Risk Models. Journal of Banking and Finance, 32:10, 2220-2236
- 2008Alexander, C. and A. Kaeck (2008) Regime-Dependent Determinants of Credit Default Swap Spreads. Journal of Banking and Finance, 32:6, 1008 - 1021.
- 2008Alexander, C. and A. Barbosa (2008) Hedging Exchange Traded Funds. Journal of Banking and Finance, 32:2, 326-337
- 2008Alexander, C. (2008) Market Risk Analysis, Volume I: Quantitative Methods in Finance. Wiley
- 2008Alexander, C. (2008) Market Risk Analysis, Volume II: Practical Financial Econometrics. Wiley
- 2008Alexander, C. (2008) Market Risk Analysis, Volume III: Pricing, Hedging and Trading Financial Instruments. Wiley
- 2008Alexander, C. (2008) Market Risk Analysis, Volume IV: Value at Risk Models. Wiley
- 2008Alexander, C. and E. Sheedy eds. (2008) The Professional Risk Manager’s Guide to Finance Theory and Application. McGraw-Hill
- 2008Alexander, C. and E. Sheedy eds. (2008) The Professional Risk Manager’s Guide to Financial Markets. McGraw-Hill
- 2008Alexander, C. and E. Sheedy eds. (2008) The Professional Risk Manager’s Guide to Financial Instruments. McGraw-Hill
- 2008Alexander, C. (2008) Hedging the risk of energy futures portfolios. Risk-Management in Commodity Markets: From Shipping to Agriculturals and Energy, H. Geman ed., Wiley
- 2008Alexander, C. (2008) Moving average models for volatility and correlation. Handbook of Finance, Volume 1, F. J. Fabozzi ed., Wiley
- 2008Alexander, C. (2008) Statistical models of operational loss. Handbook of Finance, Volume 1, F. J. Fabozzi ed., Wiley
- 2008Alexander, C. and A. Venkatramanan (2008) Commodity options. Handbook of Commodity Investing, F.J. Fabozzi, R. Fuss and D.G. Kaiser eds., Wiley
- 2007Alexander, C. and L. Nogueira (2007) Model-Free Price Hedge Ratios for Homogeneous Claims on Tradable Assets. Quantitative Finance, 7:5, 473 - 479
- 2007Alexander, C. and A. Barbosa (2007) Effectiveness of Minimum-Variance Hedging. Journal of Portfolio Management, 33:2, 46 - 59
- 2007Alexander, C. and L. Nogueira (2007) Model-Free Hedge Ratios and Scale-Invariant Models. Journal of Banking and Finance, 31:6, 1839-1861
- 2007– 2009 Editorial Board, Journal of Banking and Finance
- 2007– present Editorial Board, Journal of Portfolio Management
- 2006Yigitsbasioglu, A. and C. Alexander (2006) Pricing and Hedging Convertible Bonds: Delayed Calls and Uncertain Volatility. International Journal of Theoretical and Applied Finance, 9:2, 415-437
- 2006Alexander, C. and E. Lazar (2006) Normal Mixture GARCH: Applications to Foreign Exchange Markets. Journal of Applied Econometrics, 21:2 307-336
- 2006Alexander, C. and A. Dimitriu (2006) Rank alpha funds of hedge funds. Fund of Hedge Funds: Performance, Assessment, Diversification and Statistical Properties, G. N. Gregoriou ed., Elsevier
- 2005Alexander, C. and A. Dimitriu (2005) Rank Alpha Funds of Hedge Funds. Journal of Alternative Investments, 8:2, 48-61
- 2005Alexander, C. and A. Dimitriu (2005) Detecting Switching Strategies in Equity Hedge Fund Returns. Journal of Alternative Investments, 8:1, 7-13
- 2005Alexander, C. (2005) The Present and Future of Risk Management. Journal of Financial Econometrics, 3:1, 3-25
- 2005Alexander, C. and A. Barbosa (2005) The Spider in the Hedge. Review of Futures Markets, 11:1, 89-113
- 2005Alexander, C. and A. Dimitriu (2005) Indexing and Statistical Arbitrage: Tracking Error or Cointegration? Journal of Portfolio Management, 31:2, 50-63
- 2005Alexander, C. and A. Dimitriu (2005) Indexing, Cointegration and Equity Market Regimes. International Journal of Finance and Economics, 10, 213-231
- 2005Alexander, C. (2005) Assessment of operational risk capital. Risk Management: Challenge and Opportunity, M. Frenkel, U. Hommel and M. Rudolf eds., Springer
- 2005Alexander, C. and A. Dimitriu (2005) Hedge Fund Index Tracking. Hedge Funds: Insights in Performance Measurement, Risk Analysis, and Portfolio Allocation, G.N. Gregoriou, G. Hubner, N. Papageorgiou, and F. Rouah eds., Wiley
- 2004Alexander, C. and A. Scourse (2004) Bivariate Normal Mixture Spread Option Valuation. Quantitative Finance, 4:6 1-12
- 2004Alexander, C. (2004) Normal Mixture Diffusion with Uncertain Volatility: Modelling Short- and Long-Term Smile Effects. Journal of Banking and Finance, 28:12, 2957-2980
- 2004Alexander, C. and A. Dimitriu (2004) Sources of Out-Performance in Equity Markets: Common Trends, Mean Reversion and Herding. Journal of Portfolio Management, 30:4, 170-185
- 2004Alexander, C. and A. Dimitriu (2004) Equity Indexing: Optimising Passive Investments. Quantitative Finance, 4:3 C30 - C33
- 2004Alexander, C. and E. Sheedy eds. (2004) The Professional Risk Manager’s Handbook: Volume 1, Finance Theory, Instruments and Markets. PRMIA Publications, Illinois
- 2004Alexander, C. and E. Sheedy eds. (2004) The Professional Risk Manager’s Handbook: Volume 2, Financial Mathematics. PRMIA Publications, Illinois
- 2004Alexander, C. and E. Sheedy eds. (2004) The Professional Risk Manager’s Handbook: Volume 3, Financial Risk Management. PRMIA Publications, Illinois
- 2004Alexander C. and A. Dimitriu (2004) The Art of Investing. Hedge Funds: Fund Selection and Optimal Allocations. Intelligent Hedge Fund Investing, Barry Schachter ed., Risk Publications
- 2004Alexander, C. and L. Nogueira (2004) Stochastic local volatility. Proceedings of the second international IASTED conference on financial engineering and applications, MIT, 136-141
- 2004Alexander, C. and E. Lazar (2004) Time aggregation of normal mixture GARCH. Proceedings of the second international IASTED conference on financial engineering and applications, MIT, 210-215
- 2004Alexander, C. (2004) Principles of the skew. Exotic Options, Alexander Lipton ed., Risk Publications
- 2004Alexander, C. (2004) Correlation in crude oil and natural gas markets. Managing Energy Price Risk 3rd Edition V. Kaminsky ed., Risk Publications
- 2004Alexander, C. (2004) Advanced value-at-risk Models. Professional Risk Managers Handbook, Volume III, C. Alexander and E. Sheedy eds., PRMIA Publications
- 2004Alexander, C. (2004) Operational value-at-risk. Professional Risk Managers Handbook, Volume III, C. Alexander and E. Sheedy eds., PRMIA Publications
- 2003Alexander, C. ed. (2003) Operational Risk: Regulation, Analysis and Management. FTPrentice Hall
- 2003Alexander, C. and Pezier, J. (2003) Assessment and aggregation of banking risks. Commissioned report. International Financial Risk Institute (IFCI)
- 2003Alexander, C. (2003) Statistical models for operational loss. Operational Risk: Regulation, Analysis and Management, C. Alexander ed., Pearson
- 2003Alexander, C. (2003) Managing operational risks with Bayesian networks. Operational Risk: Regulation, Analysis and Management, C. Alexander ed., Pearson
- 2003Alexander, C. (2003) Operational risk aggregation. Operational Risk (April)
- 2003Alexander, C. (2003) Common correlation and calibrating the lognormal forward rate model. Wilmott (March), 68-78
- 2003– 2006 Expert Witness, Richards Butler, London
- 2002Alexander, C. (2002) Principal Component Models for Generating Large Covariance Matrices. Review of Banking, Finance and Monetary Economics, Economic Notes, 31:2, 337-359
- 2002Alexander, C., I. Giblin and W. Weddington (2002) Cointegration and Asset Allocation: A New Active Hedge Fund Strategy. Research in International Business and Finance, 16, 65-90
- 2002Alexander, C. (2002) Rules and models. Risk, 15:1, S2-S5
- 2002– 2012 Chair of Academic Advisory Council, Chairman of Board PRMIA
- 2001Alexander, C. (2001) Market Models: A Guide to Financial Data Analysis. Wiley
- 2001Alexander, C. ed. (2001) Mastering Risk Volume II. FT-Prentice Hall
- 2001Alexander, C. (2001) Orthogonal GARCH. Mastering Risk Volume II, C. Alexander ed., Pearson
- 2001Alexander, C. (2001) Bayesian methods for measuring operational risks. Mastering Risk Volume II, C. Alexander ed., Pearson
- 2001Alexander, C. (2001) Taking control of operational risk. Futures and Options World, 366, 60-65
- 2001Alexander, C. and J. Pezier (2001) Binomial gammas. Operational Risk (April)
- 2001Alexander, C. (2001) Taming the skew. Futures and Options World, 367, 60-65
- 2001Alexander, C. (2001) Principles of the skew. Risk 14:1, S29- S32
- 2000Alexander, C. (2000) Measuring Operational Risks with Bayesian Belief Networks. Derivatives, Use Trading and Regulation. 6:2, 166-196
- 2000Alexander, C. ed. (2000) Visions of Risk. FT-Prentice Hall
- 1999Alexander, C. (1999) Optimal Hedging using Cointegration. Philosophical Transactions of the Royal Society Series A, 357, 2039-2058
- 1999Alexander, C. (1999) Correlation and cointegration in energy markets. Managing Energy Price Risk, 2nd Edition. V. Kaminsky ed., Risk Publications
- 1998Alexander, C. ed. (1998) Risk Management and Analysis Volume I: Measuring and Modelling Financial Risk. Wiley
- 1998Alexander, C. ed. (1998) Risk Management and Analysis Volume II: New Markets and Products. Wiley
- 1998Alexander, C. (1998) Volatility and correlation: measurement, models and applications. Risk Management and Analysis: Measuring and Modelling Financial Risk. C. Alexander, ed., Wiley
- 1997Alexander, C. and C. Leigh (1997) On the Covariance Matrices used in Value-at-Risk Models. Journal of Derivatives, 4:3 50-62
- 1997Alexander, C. (1997) Estimating and forecasting volatility and correlation: methods and applications. Risk Management and Financial Derivatives: A Guide to the Mathematics, S. Das ed., LBC
- 1996Alexander, C. and I. Giblin (1996) Multivariate Embedding Methods: Forecasting HighFrequency Data in the First International Non-Linear Financial Forecasting Competition. Journal of Computational Intelligence in Finance, 5:6, 17-24
- 1996Alexander, C. and W. Ledermann (1996) Are Nash Bargaining Wage Agreements Unique? An Investigation into Bargaining Sets for Firm/Union Negotiations. Oxford Economic Papers, 48:2, 1-11
- 1996Alexander, C. and J. Wyeth (1996) Causality Testing in Models of Spatial Market Integration. Journal of Development Studies, 32:1, 144-146
- 1996Alexander, C. (1996) Evaluating the Use of RiskMetrics as a Risk Measurement Tool. Derivatives: Use Trading and Regulation, 2:3, 277-285
- 1996Alexander, C. ed. (1996) The Handbook of Risk Management and Analysis. Wiley
- 1996Alexander, C. (1996) Volatility and correlation forecasting. Handbook of Risk Management and Analysis. C. Alexander ed., Wiley
- 1996Alexander, C. and R. Thillainathan (1996) The Asian connections. Emerging Markets Investor, 2:6 42-47
- 1995Alexander, C. and H. Rendall (1995) Data Generation Processes of Spatial Series: Analysis of Ephemeral Channel Form. Geographical Analysis, 27:1, 78-93
- 1995Alexander, C. (1995) Common Volatility in the Foreign Exchange Market. Applied Financial Economics, 5:1, 1-10.
- 1994Alexander, C. and J. Wyeth (1994) Cointegration and Market Integration: an Application to the Indonesian Rice Market. Journal of Development Studies, 30:2, 303-308
- 1994Alexander, C. and M. Barrow (1994) Seasonality and Cointegration of Regional House Prices in the UK. Urban Studies, 31:10, 1667-1689
- 1994Alexander, C. and W. Ledermann (1994) The Constrained Nash Bargaining Solution. Journal of the Operational Research Society, 45:5, 954-958
- 1994Alexander, C. and A. Johnson (1994) Dynamic links. Risk, 7:2, 56-61
- 1994Alexander, C. (1994) History debunked, Risk, 7:12, 59-63
- 1994Alexander, C. and I. Giblin (1994) Chaos in the system. Risk, 7:6, 71-76
- 1993Alexander, C. (1993) The Changing Relationship between Productivity, Wages and Unemployment in the U.K. Oxford Bulletin of Economics and Statistics, 55:1, 87-102
- 1992Alexander, C. and A. Johnson (1992) Are Foreign Exchange Markets Really Efficient? Economics Letters, 40, 449-453
- 1992Alexander, C., I. Giblin and D. Newton (1992) The Symmetry of Fractals. Mathematical Intelligencer, 14:2, 32-34
- 1992Alexander, C. (1992) The Kalai-Smorodinsky Bargaining Solution in Wage Negotiations. Journal of the Operational Research Society, 43:8, 779-786
- 1992Alexander, C. and N. Riyait (1992) The world according to GARCH. Risk, 5:8, 120-125
- 1990Alexander, C. (1980-1990) The Handbook of Applicable Mathematics. Assistant editor volumes I - V and co-editor volume VI. Wiley
- 1990Alexander, C. (1990) Non-cooperative finite games. Handbook of Applicable Mathematics. Volume VI. W. Ledermann and C. Alexander eds., Wiley
- 1988Alexander, C. (1988) On a Converse to the Tschebotarev Density Theorem. Journal of the Australian Mathematical Society Series A, 44, 287-293
- 1987Alexander, C. (1987) Duality in Non-Normal Quartic Number Fields. American Mathematical Monthly, 94, 279-284
- 1985Alexander, C. and W. Ledermann (1985) Integral Bases of Dihedral Number Fields. Journal of the Australian Mathematical Society Series A, 38, 351-371
- 1984Alexander, C. (1984) Evaluation of index-linked gilts using inflation forecasts. The Investment Analyst, 72, 7-12
- 1980Alexander, C. (1980) Groups. Handbook of Applicable Mathematics, Volume I. W. Ledermann ed., Wiley
- Journal Articles
- Authored Books
- Edited Books
- Book Chapters, Reports and Conference Papers
- Practitioner Journal Articles
Positions & affiliations17
- University of Sussex
- University of Reading
- TU Munich
- Peking University
- 1977 – 1978 Editor, John Wiley (one year interim PhD research)
- 1981 – 1982 Postdoctoral Research Fellow, University of Amsterdam
- 1982 – 1983 Bond Analyst, UBS Phillips and Drew, London
- 1983 – 1985 Teaching and Research Assistant, London School of Economics (part-time)
- 1985 – 1996 Lecturer in Mathematics and Economics, University of Sussex
- 1996 – 1998 Lecturer in Mathematics, University of Sussex (part-time)
- 1996 – 1998 Academic Director, Algorithmics Inc., London (part-time)
- 1998 Director, Head of Market Risk Modelling, Nikko Securities, London
- 1998 – 1999 Visiting Research Fellow, Oxford Centre for Industrial and Applied Mathematics
- 1999 – 2012 Chair of Financial Risk Management, ICMA Centre, Henley Business School
- 2012 – present Professor of Finance, University of Sussex
- 2013 – 2014 Head of Business and Management (now University of Sussex Business School)
- 2019 – present Visiting Professor, Peking University
Credentials & fellowships3
- Journal of Banking & Finance, Financial Analysts Journal, Finance & Stochastics, Quantitative Finance, Journal of Portfolio Management, Journal of Futures Markets, Journal of Economic Dynamics & Control, Journal of Applied Econometrics, Journal of Financial Econometrics, Journal of Business Finance & Accounting, European Financial Management, Annals of Econometrics, Applied Mathematical Finance, Journal of Alternative Investments, Applied Financial Economics, European Journal of Finance, European Journal of Operational Research, Review of Finance, Review of Financial Studies
- 2009 U.S. Patent Number 7,571,130: Hedging exchange traded mutual funds or other portfolio basket products
- 2011 U.S. Patent Number 7,979,336: A system for pricing financial instruments
Honours & awards13
- 1996 Winner, First International Non-Linear Financial Forecasting Competition (with Ian Giblin)
- 2002 Honorary Professorship, Academy of Economic Sciences, Bucharest
- 2003 International Financial Risk Institute (IFRI), 9th Roundtable Award
- 2007 Professional Risk Managers International Association (PRMIA) Higher Standard Award (with Robert Merton)
- 2010 University of Reading award for outstanding contributions to teaching and learning
- 1981 Leverhulme Foundation Post-Doctoral Award
- 1986 Nuffield Foundation Award for New Science Lecturers
- 1994 ESRC: Chaos in Financial Markets
- 2003 Foundation for Managed Derivatives Research
- 2003 British Academy (with Simon Burke, Henley Business School)
- 2005 Australian Prudential Regulatory Authority (with Elizabeth Sheedy, Macquarie)
- 2008 Europlace Institute of Finance (with Steve Ohana, ESCP-EAP)
- 2014 Global Risk Institute (with Andreas Kaeck)